Module 3: Analysis of Financial Statements — Notes
(Accounting for Managers – ACCT602, Semester I)
✅ Verified against the live AMIGO course — started in-LMS 2026-09-26 (session 4/5), being walked lesson-by-lesson (24 lessons total) with real content folded in as ✅ callouts below. Structure: Learning Objectives → Introduction → 3.1 Comparative Statement Analysis → 3.2 Ratio Analysis → 3.3 DuPont Analysis → 3.4 Cash Flow Statement (approximate, per live SCORM sidebar).
Lesson 1-2: Learning Objectives & Introduction
✅ Live course confirms this module covers: overview of financial statement + trend analysis, comparative balance sheet horizontal/vertical analysis, an inter-firm comparison case study, profitability/liquidity/solvency/turnover ratios, DuPont decomposition analysis, and cash flow statement preparation (direct + indirect method) with a numerical.
The live Introduction lesson's own diagram shows Financial Statement Analysis radiating into six analysis types (not just the three in the mermaid diagram below): Horizontal Analysis, Vertical Analysis, Regression Analysis, Trend Analysis, Ratio Analysis, Graphical Analysis. Financial analysis = identifying a firm's strengths/weaknesses via balance sheet ↔ income statement relationships; can be done by management or external parties (owners, creditors, investors, analysts) each with different interests. Tools help assess: continuity of operating policies, investment value, credit ratings, operational efficiency, and support financial control (regular review, deviation analysis, corrective action).
Lesson 3: 3.1.1 Overview of Financial Statement Analysis
✅ Verified against the live course (Lesson 3, video 07:10): presented by Dr. Geetika Batra. Financial statement analysis = evaluating a company's financial statements (balance sheet, income statement) to assess financial health/performance and identify strengths/weaknesses. Techniques listed: comparative statements, schedule of changes in working capital, common size percentages, funds analysis, trend analysis, ratios analysis. Financial statements alone don't yield conclusions — meaningful insight comes only through analysis + interpretation.
3-tab widget (all tabs clicked): Horizontal Analysis/Trend Analysis (comparison of 2+ years' data, shown in both $ and % form); Trend Percentage — a horizontal-analysis technique that states several years' data in terms of a base year = 100%, other years as a % of that base; Vertical Analysis — preparing/presenting common-size statements, each item as a % of some total, highlighting key changes/trends.
Quiz: "Primary purpose of financial statement analysis" → To assess financial health of the firm. "NOT a commonly used financial statement for analysis" → Tax return statement (vs. balance sheet, cash flow statement, income statement, which are the three core financial statements).
3.1 Comparative Statement Analysis
Financial Statement Analysis = Analysis (simplifying data) + Interpretation (explaining significance). Used to assess profitability, efficiency, financial health.
Horizontal Analysis (Trend Analysis)
- Compares data across 2+ years; one year = base year (100%).
- Formulas:
- Absolute Change = Current Period Value − Previous Period Value
- % Change = (Absolute Change ÷ Previous Period Value) × 100
- Good for spotting trend direction (uptrend/downtrend/sideways) across years.
- Limitation: choice of base year can distort the picture; segment restructuring can break comparability.
Vertical Analysis (Common-Size Statements)
- Each line item expressed as % of a base item within the same period:
- Balance Sheet → base = Total Assets
- Income Statement → base = Net Sales
- Useful to compare companies of different sizes (standardises the statements).
flowchart LR
    A[Financial Statement Analysis] --> B["Horizontal / Trend Analysis (across years, base year = 100%)"]
    A --> C["Vertical / Common-Size Analysis (within one year, base = Total Assets or Net Sales)"]
    A --> D["Ratio Analysis (relationships between line items)"]
🧠 Memory trick — Horizontal vs Vertical: Horizontal = History (compares across years/history); Vertical = Vs-each-other-within-one-year (compares line items as a % of one base, standing "vertically" down a single column).
Horizontal vs Vertical — Exam favourite
| Basis | Horizontal | Vertical |
|---|---|---|
| Comparison | Across multiple periods | Within a single period |
| Base | Base year = 100% | Base item (Total Assets/Sales) = 100% |
| Other name | Trend Analysis | Common-Size Analysis |
| Best for | Growth trend over time | Comparing companies of different sizes |
3.2 Ratio Analysis — the most exam-critical section
🧠 Memory trick for the 5 ratio categories — "Please Learn Some Tough Exams": Profitability, Liquidity, Solvency, Turnover/Efficiency, Earning.
A. Profitability Ratios
| Ratio | Formula |
|---|---|
| Gross Profit Ratio | Gross Profit ÷ Sales × 100 |
| Net Profit Ratio | Net Profit ÷ Sales × 100 |
| Operating Ratio | (COGS + Operating Expenses) ÷ Net Sales × 100 |
| Return on Assets (ROA) | Net Profit after Tax ÷ Average Total Assets × 100 |
| Return on Capital Employed (ROCE) | Net Profit after Tax ÷ Total Capital Employed × 100 |
B. Liquidity Ratios (short-term solvency)
| Ratio | Formula | Ideal |
|---|---|---|
| Current Ratio | Current Assets ÷ Current Liabilities | ≈ 2:1 |
| Acid-Test / Quick Ratio | (Current Assets − Stock − Prepaid Exp.) ÷ Current Liabilities | ≈ 1:1 |
C. Solvency Ratios (long-term)
| Ratio | Formula |
|---|---|
| Debt-Equity Ratio (long-term) | Long-term Debt ÷ Net Worth (Shareholders' Funds) |
| Total Debt-Equity Ratio | (Short-term + Long-term Debt) ÷ Equity |
| Proprietary Ratio | Net Worth ÷ Total Assets |
| Solvency Ratio | Total Assets ÷ Total Liabilities |
D. Turnover / Efficiency Ratios
| Ratio | Formula |
|---|---|
| Stock Turnover Ratio | COGS ÷ Average Stock |
| Debtors Turnover Ratio | Net Credit Sales ÷ (Debtors + Bills Receivable) |
| Debtors Velocity (collection period) | 365 ÷ Debtors Turnover Ratio |
| Creditors Turnover Ratio | Credit Purchases ÷ Average Creditors |
| Creditors Velocity (payment period) | 365 ÷ Creditors Turnover Ratio |
E. Earning Ratios
- EPS = (Net Profit − Preference Dividend) ÷ No. of Equity Shares
- DPS = Dividend paid to equity shareholders ÷ No. of Equity Shares
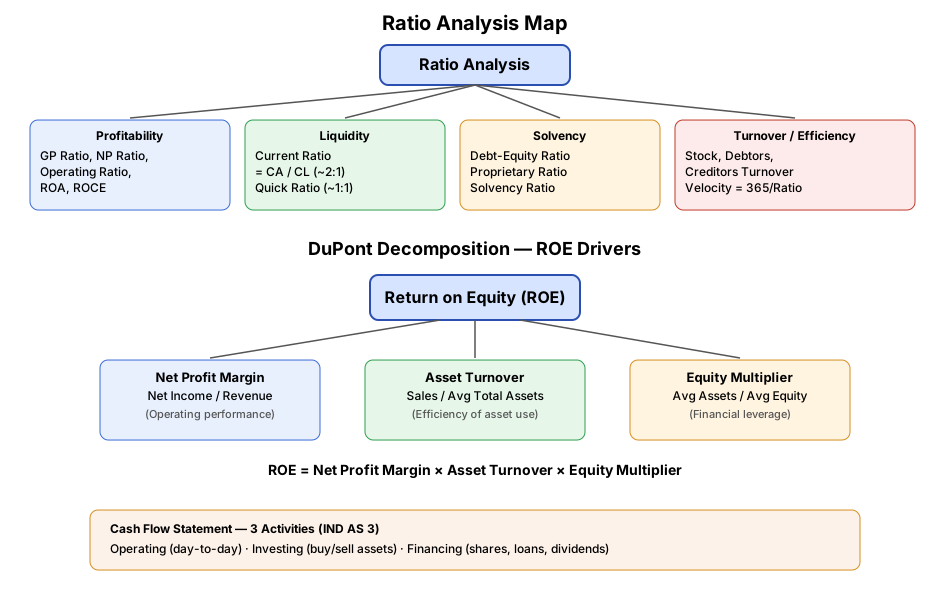
F. DuPont Decomposition — very high-yield topic
ROE = Net Profit Margin × Asset Turnover × Equity Multiplier - Net Profit Margin = Net Income ÷ Revenue - Asset Turnover = Sales ÷ Average Total Assets - Equity Multiplier = Average Total Assets ÷ Average Shareholders' Equity
flowchart LR
    ROE["Return on Equity (ROE)"] --> NPM["Net Profit Margin\n(Net Income / Revenue)"]
    ROE --> AT["Asset Turnover\n(Sales / Avg Total Assets)"]
    ROE --> EM["Equity Multiplier\n(Avg Assets / Avg Equity)"]
Why it matters: shows whether ROE is driven by profitability, efficiency, or leverage — a classic case-study/discussion question.
🧠 Memory trick — DuPont's 3 levers, "PEA": Profit margin, Efficiency (asset turnover), Amplification (equity multiplier/leverage) — ROE = P × E × A.
3.3 Cash Flow Statement (as per IND AS 3)
Shows sources and uses of cash — explains the change in cash balance between two balance sheet dates.
Three Activities
flowchart TD
    CFS[Cash Flow Statement] --> OA["Operating Activities\n(day-to-day business: cash from customers, payments to suppliers/employees)"]
    CFS --> IA["Investing Activities\n(purchase/sale of fixed assets, investments)"]
    CFS --> FA["Financing Activities\n(issue of shares/debentures, loan repayment, dividend paid)"]
Direct vs Indirect Method (for Operating Activities only)
| Method | Approach |
|---|---|
| Direct | Lists actual cash receipts and payments (cash from customers − cash to suppliers/employees, etc.) |
| Indirect | Starts from Net Profit, then adjusts for non-cash items (add back depreciation) and changes in working capital (± change in current assets/liabilities) — most commonly used & tested |
Indirect Method — Quick Structure:
Net Profit before Tax
+ Depreciation & non-cash expenses
± Changes in Working Capital (increase in CA = subtract, increase in CL = add)
= Cash from Operating Activities
Long-Answer Questions (15 Marks — model answers, ~300 words each)
Q1. Differentiate between Horizontal and Vertical Analysis, and explain their significance in financial statement analysis. Horizontal and Vertical Analysis are the two basic techniques used to simplify and interpret financial statements before deeper ratio analysis is applied. Horizontal Analysis, also called Trend Analysis, compares the same line item across two or more accounting periods — one period is chosen as the base year (set at 100%), and every subsequent year's figure is expressed both as an absolute change (Current Value − Previous Value) and a percentage change [(Absolute Change ÷ Previous Value) × 100] relative to that base. This lets an analyst spot whether sales, expenses, or profits are trending up, down, or sideways over time, and by how much — for instance, seeing that Net Sales grew 12% while COGS grew 20% immediately signals margin pressure worth investigating. Its main limitation is that the chosen base year itself must be "normal" — if the base year was unusually good or bad (e.g., a one-off asset sale, or a pandemic-hit year), every subsequent percentage comparison gets distorted. Vertical Analysis, also called Common-Size Analysis, instead expresses every line item as a percentage of one base item within the same period — for the Balance Sheet, the base is Total Assets; for the Income Statement, the base is Net Sales. This converts absolute rupee figures into comparable proportions, making it possible to compare a small company against a much larger one on a like-for-like basis (e.g., "COGS is 60% of sales" is comparable across companies of any size, whereas "COGS is ₹6 crore" is not). The key distinction, then, is that Horizontal Analysis looks across time to reveal trend and growth patterns, while Vertical Analysis looks within one period to reveal structural composition and enables cross-company comparison. In practice, analysts use both together — vertical analysis to understand a company's current cost/asset structure, and horizontal analysis to see how that structure and scale are evolving year over year — giving a fuller diagnostic picture than either technique alone.
Q2. Explain the key ratios used to assess a company's liquidity and solvency, with their formulas and significance. Liquidity ratios measure a company's ability to meet its short-term obligations, while solvency ratios measure its ability to meet long-term obligations and its overall capital structure risk — together they answer "can this company pay what it owes, both soon and eventually?" The Current Ratio (Current Assets ÷ Current Liabilities) is the broadest liquidity measure, with an ideal benchmark of roughly 2:1, meaning the company holds twice as many short-term resources as short-term obligations; a ratio well below 1 signals possible difficulty paying bills on time, while an excessively high ratio can indicate idle, poorly-utilised current assets. The Quick/Acid-Test Ratio [(Current Assets − Inventory − Prepaid Expenses) ÷ Current Liabilities], ideally around 1:1, is a stricter test because it excludes inventory (which may be slow-moving or hard to liquidate quickly) and prepaid expenses (which can't be converted to cash at all) — it answers "can the company pay creditors without relying on selling stock?" On the solvency side, the Debt-Equity Ratio (Total/Long-term Debt ÷ Shareholders' Equity) measures financial leverage — how much of the business is financed by outside borrowing versus owners' funds; a high ratio means higher fixed interest obligations and higher financial risk, especially if profits dip. The Proprietary Ratio (Net Worth ÷ Total Assets) shows what proportion of total assets is funded by owners rather than creditors — a higher ratio indicates a more conservatively financed, lower-risk balance sheet. The Interest Coverage Ratio (EBIT ÷ Interest Expense) shows how comfortably operating profits cover interest obligations — a ratio below 1.5–2 is often a red flag for lenders. Together, liquidity ratios protect against near-term cash crunches, while solvency ratios protect against long-term over-leverage; a company can look solvent on paper (low debt) yet still fail from a liquidity crunch, which is why both sets of ratios must be read together, not in isolation.
Q3. Explain DuPont Analysis. How does it decompose Return on Equity (ROE), and why is this decomposition useful? DuPont Analysis is a technique that breaks down Return on Equity — the single most-watched profitability metric for shareholders — into three distinct drivers, revealing why a company's ROE is high or low rather than just reporting the final number. The formula is ROE = Net Profit Margin × Asset Turnover × Equity Multiplier. The Net Profit Margin (Net Income ÷ Revenue) captures profitability — how much profit the company keeps from every rupee of sales, driven by pricing power, cost control, and operating efficiency. The Asset Turnover Ratio (Sales ÷ Average Total Assets) captures efficiency — how effectively the company uses its asset base to generate revenue, driven by inventory management, capacity utilisation, and receivables collection. The Equity Multiplier (Average Total Assets ÷ Average Shareholders' Equity) captures financial leverage — how much of the asset base is funded by debt rather than equity; a higher multiplier means more leverage, which amplifies ROE but also amplifies risk. The power of this decomposition is diagnostic: two companies can report an identical 15% ROE for completely different reasons — one might achieve it through high margins and modest leverage (a quality, low-risk business), while another achieves the same ROE only by taking on heavy debt to multiply a thin margin (a risky, leverage-driven business). An investor or manager relying on ROE alone would treat both companies as equally attractive, but DuPont analysis exposes the difference, making it invaluable for comparing companies within an industry, diagnosing a declining ROE trend (has margin fallen, has efficiency dropped, or has the company simply deleveraged?), and setting management performance targets that don't inadvertently reward excessive risk-taking through leverage alone. This is precisely why DuPont analysis is a favourite case-study and discussion topic in management accounting.
Q4. What is a Cash Flow Statement? Explain its three main activities with examples, and distinguish between the Direct and Indirect methods. A Cash Flow Statement (prepared under Ind AS 7 / AS 3) explains the change in a company's cash and cash-equivalent balance between two Balance Sheet dates by classifying all cash movements into three activities. Operating Activities cover the cash effects of the company's core, day-to-day revenue-generating operations — cash received from customers, cash paid to suppliers and employees, and cash paid for operating expenses and taxes; this is the most important section because it shows whether the core business itself is cash-generative. Investing Activities cover cash flows related to the acquisition and disposal of long-term assets and investments — for example, purchase of plant and machinery, proceeds from sale of a fixed asset, or purchase/sale of long-term investments; a growing company typically shows negative investing cash flow (spending on growth), which is not necessarily a bad sign. Financing Activities cover cash flows between the company and its owners/lenders — proceeds from issuing shares or debentures, repayment of loans, and dividends paid; this section reveals how the company is funding itself and rewarding capital providers. Operating cash flow specifically can be computed by either the Direct Method, which lists actual gross cash receipts and payments (cash from customers minus cash to suppliers, employees, etc.) giving a very transparent but data-intensive picture, or the far more commonly used Indirect Method, which starts from Net Profit before Tax and works backward: add back non-cash expenses like depreciation (since they reduced profit but didn't use cash), then adjust for changes in working capital — an increase in current assets (like debtors or stock) is subtracted (cash is tied up), while an increase in current liabilities (like creditors) is added back (cash is preserved) — arriving at Cash from Operating Activities. The Indirect Method is preferred in practice and in exams because it directly reconciles profit with cash, highlighting the gap between "accounting profit" and "actual cash generated," which is often the crux of a case-study question on why a profitable company still faces a cash crunch.
Live Lesson Captures (Lessons 4 onward, verified against the live AMIGO course, session 9, 2026-10-01)
Lesson 4: 3.1.2 Trend Analysis (reading time 10 min, SLM p.101-103)
- Trend analysis uses financial statements to identify market trends and project future performance: data from records is plotted on a graph and trend lines join data points so analysts can see upward and downward tendencies; historical data is used to forecast future trends in a sector. Purpose: evaluate how a market has changed over a period (year-over-year trend analysis for long-term data; monthly trend analysis for the short term).
- Reasons patterns change: stock supply changes vs shares offered, new laws, market volatility.
- Advantages (3 tabs): Financial gain (well-informed forecasts of when to buy stocks/assets; a bull market run is an uptrend where values rise 20% or more after a market bottom); Recognising the elements of a successful business (which tactics work, which need tweaking; knowledge of asset/stock prices informs short- and long-term strategy); Comprehending market dynamics (monitoring upward/downward movement improves understanding of financial and economic trends).
- Three kinds of trends: Uptrend (bull market: rising prices, economic expansion, more jobs, start of an investment cycle; identified by higher peaks and troughs), Downtrend (bear market: worsening markets, falling asset values, firms closing or reassessing, revenue declines; fewer peaks/troughs), Horizontal (sideways) trend (values broadly stable, neither rising nor falling; investors find the direction hard to judge, experts may not predict short/long-term events).
- Examples: sales patterns; expenditure records (check charges are authorised); budget forecasting; expense tracking (spot unusual line items).
- Video note: the Vimeo video that blocked this lesson in earlier sessions is NOT required - the lesson unlocked after widgets + quizzes + a full slow scroll without playing it.
Lesson 5: 3.1.3 Comparative Balance Sheet - Horizontal Analysis (15 min, SLM p.103-107)
- Horizontal (base-year/trend) analysis compares line items and ratios across accounting periods, stating each later period as a percentage of the base year (100%); can use absolute or percentage comparisons. Steps: (1) select comparative periods, (2) calculate absolute change = current - previous, (3) percentage change = absolute change / previous-year amount x 100.
- Standards: GAAP's consistency (same principles each year) and comparability (comparable with other firms in the industry) requirements; analysts can spot growth drivers, seasonality and relative product-line change. Metrics: profit margin, inventory turnover, ROE, coverage ratios (interest coverage, cash flow-to-debt).
- Drawbacks: results depend on the chosen base year/periods (the current period can be made to look unusually good or bad); data compilation may change over time; some firms resegment the business to manipulate trends.
- Worked example (Bruno Corporation, 2023 vs 2024) - 14 hotspots: Cash +Rs150,000 (+20.0%, better liquidity); Accounts receivable -Rs37,500 (-10.0%, faster collection or lower credit sales); Inventory +Rs75,000 (+14.3%, higher demand expectations or overstocking); Total current assets +Rs187,500 (+11.4%); PP&E +Rs375,000 (+16.7%, expansion/upgrade); Total assets +Rs562,500 (+14.4%); Accounts payable +Rs37,500 (+12.5%); Short-term loans -Rs37,500 (-16.7%, repayment); Total current liabilities unchanged; Long-term debt +Rs150,000 (+10.0%); Total liabilities +Rs150,000 (+7.4%); Retained earnings +Rs412,500 (+36.7%); Total equity +Rs412,500 (+22.0%); Total liabilities & equity +Rs562,500 (+14.4%) = asset growth (balance sheet equation holds).
Lesson 6: 3.1.4 Comparative Income Statement - Horizontal Analysis (14 min, SLM p.107-110)
- A comparative income statement shows operating results over several periods and lets you examine line-by-line changes. Look at: sales vs cost of goods sold; operating profit changes; overall profitability (net profit changes).
- Procedure (3-step carousel): (1) list exact amounts for all items for the periods (Columns I and II); (2) compute the absolute change (Column III) = current - prior year; (3) compute the percentage change (Column V).
- Two forms (tabs): Horizontal analysis (shows change in absolute and % terms; easy to see growth trends and seasonality; = trend analysis) and Vertical (common-size) analysis (each item as a % of a base such as sales; easy comparison across firms of different size).
- Practical applications (5): identifying trends; comparing performance (operating income growth = efficiency/cost control); identifying areas of concern (rising operating expense relative to revenue); assessing financial health; supporting decisions (investors, lenders, strategy).
- Example: ABC Limited comparative income statement, years ended 2016 and 2017.
Lesson 7: 3.1.5 Comparative Balance Sheet - Vertical Analysis (15 min, SLM p.110-112)
- Vertical (common-size) analysis expresses every line item as a % of a base item in the same period: balance sheet base = total assets (liabilities/equity side uses total liabilities and equity), income statement base = total revenue/net sales. Typically a single period; best combined with horizontal analysis; also compares companies of different sizes.
- Steps (3-step carousel): select the base item; compute % = (individual item / base item) x 100; interpret relative importance and trends/anomalies.
- Practical applications (5): asset composition (e.g. capital-intensive firms have more fixed assets), liabilities and equity (leverage/financial structure), comparing companies, identifying trends (rising debt, shift to equity), financial-health snapshot. In the course example only 25% of assets are fixed; the bulk are current.
Lesson 8: 3.1.6 Comparative Income Statement - Vertical Analysis (15 min, SLM p.113-115)
- Income statement vertical analysis = each line item as a % of sales (common-size statement); helps track upward/downward performance, compare firms in the same industry, and lets management judge marketing/sales strategy.
- Steps (4-step carousel): gather the income statement; decide the basis (sales = 100%); calculate % = item / sales x 100; set up the table (e.g. Excel) against each line item.
- Benefits: simple to comprehend and interpret; time-series analysis of costs, payroll, operating and gross profit, net profit; analysis from the common-size sheet at a glance; helps analyse structural composition (marketing, depreciation, amortisation, wages).
- Limitations (6): no standard ratios (apart from profit margins); price-level changes/inflation not adjusted; accounting-principle consistency needed; seasonal fluctuations; window dressing hard to detect; only quantitative (ignores qualitative actions like marketing innovation).
- Example (Bruno Corporation): COGS = 50.0% of revenue; operating income = 30.0% of revenue.
Lesson 9: 3.1.7 Inter Firm Comparison (14 min, SLM p.115-118)
- Inter-firm (cross-sectional) comparison compares a company's financial performance and position with other firms in the same industry or with industry averages, using firms similar in sales, asset size and market share.
- Steps (5-step carousel): (1) select comparable firms (similar size, industry, market); (2) gather financial statements (income statement, balance sheet, cash flow); (3) calculate key ratios (profitability, liquidity, leverage, efficiency); (4) compare the focal firm's ratios with peers; (5) identify trends over time relative to peers.
- Practical applications (5 accordions): profitability (net profit margin, ROE); liquidity (current, quick ratio); leverage (debt-to-equity, interest coverage); efficiency (inventory turnover, asset turnover); valuation (P/E, P/B).
- Case (Indian fertiliser firms, 2020): National Fertilizers Ltd is the largest by sales but not the most profitable; Fertilisers & Chemicals Travancore Ltd has the highest net profit margin (35%).
Lesson 10: 3.2.1 Ratio Analysis Part 1 - Profitability Ratios (13 min, SLM p.118-120)
- Profitability ratios measure profit in three dimensions: sales, investments and capital employed.
- Gross profit ratio = gross profit / net sales x 100 (profit per Rs 1 of turnover before administration and selling costs; should be much higher than net margin). Example: GP Rs 4,00,000 on sales Rs 20,00,000 = 20%.
- Net profit ratio = net profit / net sales x 100 (overall earning capacity on sales).
- Operating profit ratio (operating ratio) relates cost of goods sold plus operating expenses to sales.
- Return on assets = net profit after tax / total assets x 100 (how well assets are used).
- ROCE = profit / capital employed x 100, where capital employed = non-current liabilities + shareholders' equity.
Lesson 11: 3.2.2 Ratio Analysis Part 2 - Liquidity Ratios (10 min, SLM p.120-121)
- Liquidity = short-term solvency. Two ratios: current ratio and acid-test (quick) ratio.
- Current ratio (working-capital ratio) = current assets / current liabilities. Current assets: cash, bank, marketable securities, stock, accrued incomes, prepaid expenses; current liabilities: creditors, short-term debt, outstanding expenses, unearned income. Limitation: all current assets are weighed equally. Example: Rs 5 lac / Rs 2 lac = 2.5 : 1.
- Acid-test (quick) ratio = quick assets / current liabilities, where quick assets exclude inventory (and prepaid expenses): a stricter test. Example: (55,000 - 30,000 - 10,000) / 15,000 = 1 : 1.
- Gross working capital = total current assets (net working capital = current assets - current liabilities).
Lesson 12: 3.2.3 Ratio Analysis Part 3 - Solvency Ratios (16 min, SLM p.121-123)
- Solvency (long-term) ratios show ability to meet long-term obligations (debentures, long-term loans, unpaid hire-purchase instalments, long-term creditors).
- Debt-equity ratio: long-term D/E = long-term debt / shareholders' funds; total D/E = total debt / shareholders' funds (example: (3 + 1) crore / 5 crore = 0.8 : 1). Low owner contribution makes recovery of outsiders' money harder in liquidation.
- Proprietary ratio = owners' equity (net worth) / total assets (higher = more owner funding).
- Coverage ratios (ability to meet fixed financial obligations): interest coverage = EBIT / interest (example: 4,00,000 / 40,000 = 10 times, high safety); also called debt service coverage in the course text; dividend coverage = profit after tax / preference dividend (example: 3,00,000 / 60,000 = 5 times).
Lesson 13: 3.2.4 Ratio Analysis Part 4 - Turnover Ratios (30 min, SLM p.123-126)
- Turnover ratios link sales with assets and show how fast assets convert to sales.
- Stock turnover = cost of goods sold / average stock (example: 5,00,000 / ((40,000+60,000)/2) = 10 times).
- Debtors turnover = credit sales / average debtors (+ bills receivable); average collection period = days in year / debtors turnover.
- Creditors turnover = credit purchases / average creditors (+ bills payable); creditors velocity = days / creditors turnover (worked example with sales Rs 1,00,000, GP 10%, opening stock 10,000, closing stock 20,000, velocity 73 days, bills payable 16,000, all purchases on credit).
Lesson 14: 3.2.5 Ratio Analysis Part 5 - Earning Ratios (30 min, SLM p.126-128)
- Earnings per share (EPS) = (net profit after tax - preference dividend) / number of equity shares: earnings available to equity shareholders.
- Dividend per share (DPS) = dividends paid to equity shareholders / number of shares: EPS shows what shareholders earned, DPS what they were actually paid.
- EPS is the key component of the price-to-earnings (P/E) ratio. Worked balance-sheet example (31-3-06): current ratio, stock to working capital, debt-equity, net-worth (proprietary), fixed assets to net worth, current assets to net worth, solvency ratio.
Lesson 15: 3.3 DuPont Decomposition Analysis (6 min, SLM p.128)
- DuPont analysis decomposes ROE into three drivers: operating performance (net profit margin), asset-use efficiency (asset turnover), financial leverage (equity multiplier).
- ROE = Net profit margin x Asset turnover x Equity multiplier. Net profit margin = net income / revenue; asset turnover = sales / average total assets; equity multiplier = average total assets / average shareholders' equity.
- Helps investors see the strengths and weaknesses behind ROE separately (6 info markers on the formula).
Lesson 16: Cash Flow Statement - Overview and Benefits (as per Ind AS 3 / AS 3) (8 min, SLM p.128-129)
- The cash flow statement lists all sources and uses of cash over a period. Sources: revenues, long-term financing, sale of non-current assets, increase in current liabilities, decrease in current assets. Uses: operating losses, debt repayment, equipment purchases, increase in current assets.
- Objectives (4 markers): liquidity/solvency information and ability to change cash flows; additional information on changes in assets, liabilities and equity; better comparability of operating performance across firms by removing accounting-method effects; amount, timing and probability of future cash flows.
- Benefits to users (5): equity investors and lenders (track investment, assess management); finance specialists (buy/sell/hold advice); credit rating agencies; customers and suppliers (financial strength); labour unions (pay-rise capacity).
Lesson 17: Classification of Activities for the Cash Flow Statement (16 min, SLM p.129-134)
- Three activity classes: Operating (day-to-day operations), Investing (investments for later benefit, e.g. sale/purchase of equipment, property, short-term investments), Financing (all financial transactions: issuing shares, borrowing/repaying loans, short-term borrowing).
- Gym example (9 markers): advertisements and instructors = operating; short-term loan, certificate of deposit, issue of new shares = financing; startup investment, fixed deposits, building for a new centre, sound-system upgrade = investing.
- Cash balance rules: liabilities up = cash up; liabilities down = cash down; assets up = cash down; assets down = cash up.
- Total cash flow = net operating CF + net investing CF + net financing CF.
- Direct method shows actual cash inflows/outflows of operations; indirect method starts with net income: (1) start with net income; (2) add back non-cash charges (depreciation, amortisation); (3) add back losses, subtract gains from investing/financing; (4) adjust for changes in operating working-capital accounts (increase in assets = subtract; decrease in assets = add; increase in liabilities = add; decrease in liabilities = subtract). Investing and financing flows are the same under both.
- Takeouts: cash flow shows the true cash position; investors should check operating cash flow closely.
Lesson 18: Preparation of Cash Flow Statement - Numerical/Example (26 min, SLM p.134-138)
- Worked examples: Om Ltd (balance sheet + P&L at 31-3-06, building sold at cost Rs 36,000; provision for tax, building, depreciation provision and adjusted P&L accounts prepared, then the cash flow statement as per AS 3) and Ambuja Co. Ltd (2012 vs 2013 statements of financial position, income statement, retained earnings; cash flow statement).
Lesson 19: Summary (Module 3)
- Financial statement analysis evaluates a company's statements to assess financial health and spot strengths and weaknesses.
- Trend lines join data points to show up/down tendencies; historical data is used to forecast sector trends.
- Vertical analysis (single period) is most powerful when combined with horizontal analysis.
- Vertical analysis of the income statement expresses each line as a % of sales.
- Ratio analysis (profitability, liquidity, solvency, efficiency) is the fundamental tool.
- Solvency ratios show ability to meet long-term obligations.
- Turnover ratios show speed of converting assets into sales.
- DuPont analysis decomposes ROE.
- The direct method gives a more easily understood report but the indirect method is almost universally used (standards require an indirect-style reconciliation).
- Indirect method starts from net income and adjusts for items affecting income but not cash.
- Non-cash/non-operating costs are added back to net income and non-cash/non-operating credits excluded to get operating profit before working-capital changes.
Lesson 20: Glossary (Module 3)
- Trend analysis: analysing statements to identify market trends and project future performance by plotting historical data and analysing trend lines.
- Horizontal analysis: historical data across periods, each value expressed as a % of the baseline year.
- Vertical analysis: one period, each income-statement line as a % of sales.
- Solvency ratios: ability to meet long-term obligations (long-term solvency ratios).
- DuPont analysis: decomposes ROE into components to identify strengths and weaknesses.
Lesson 21: Check Your Understanding (5 questions, scored 100%)
See Quiz Bank Q33-37.
Lesson 22: Exercise (self-study)
- How does horizontal analysis of a balance sheet differ from vertical analysis?
- What are the key benefits of the DuPont decomposition analysis?
- Explain how liquidity ratios are used to assess a company's financial health.
- What are solvency ratios and why are they important?
- How does the direct method of preparing a cash flow statement differ from the indirect method?
Lesson 23: Learning Activities (self-study)
- Given the balance sheet and income statement of a fictitious company, calculate profitability (ROA, ROE), liquidity (current, quick) and solvency (debt-to-equity) ratios and discuss what each says about financial health.
- Given financial statements of two companies in the same industry, do horizontal and vertical analysis, identify trends, similarities and differences, and draw conclusions on relative financial health and operational efficiency.
Lesson 24: Further Readings and Bibliography
- Horngren, C.T., Accounting for Management Control - An Introduction, Prentice Hall, 1965.
- Maheswari, S.N., Management Accounting, Sultan Chand & Sons.
- Hingorani, Ramanathan & Grewal, Management Accounting.
- Jain S.P. and Narang K.L., Cost Accounting; Tulsian, Financial Accounting, Tata McGraw-Hill.
✨ Quick Revision Pack (Module 3)
60-second summary
- Financial statement analysis converts raw statements into insight. Tools: comparative statements, common-size (vertical) analysis, trend (horizontal) analysis, ratio analysis, cash flow statement.
- Horizontal analysis: compare years; base year = 100. Vertical analysis: each item as % of a base (revenue or total assets).
- Ratio families: liquidity (current, quick), solvency (debt-equity, interest coverage), profitability (margins, ROA, ROE), activity/efficiency (turnover ratios).
- Cash flow statement (Ind AS 7): operating, investing, financing activities; indirect method adjusts profit for non-cash items and working-capital changes.
Diagrams
Ratio analysis map
flowchart TB
  R["Ratio analysis"] --> L["Liquidity
can we pay short-term bills?"]
  R --> S["Solvency
can we pay long-term debt?"]
  R --> P["Profitability
how much do we earn?"]
  R --> A["Activity / efficiency
how well do we use assets?"]
  L --> L1["Current ratio, Quick ratio"]
  S --> S1["Debt-equity, Interest coverage"]
  P --> P1["Gross / net margin, ROA, ROE"]
  A --> A1["Inventory, debtors, creditors, asset turnover"]
Cash flow statement structure
flowchart TB
  C["Cash flow statement"] --> O["Operating activities
core business cash"]
  C --> I["Investing activities
buy / sell assets, investments"]
  C --> F["Financing activities
shares, loans, dividends"]
  O & I & F --> N["Net change in cash + opening cash = closing cash"]
DuPont breakdown of ROE
flowchart LR
  ROE["ROE"] --> A["Net margin = PAT / Sales"]
  ROE --> B["Asset turnover = Sales / Assets"]
  ROE --> C["Equity multiplier = Assets / Equity"]
Memory tricks
Liquidity = short term, Solvency = long term. Current & quick ratios = liquidity; debt-equity & interest coverage = solvency.
Quick ratio = (Current assets - Inventory) / Current liabilities – "quick" assets can be turned into cash fast, so inventory (and prepaid) are excluded; it is the stricter test.
Higher debt-equity = more leverage = more risk. High interest coverage = comfortable ability to pay interest.
Cash flow classification: buying machinery → investing outflow; issuing shares → financing inflow; collecting from customers → operating inflow; dividends paid → financing.
Ratios mislead if used alone: compare with past years, competitors and industry norms.
Formula sheet
| Ratio | Formula | Ideal / meaning |
|---|---|---|
| Current ratio | CA / CL | about 2:1 |
| Quick ratio | (CA - Inventory) / CL | about 1:1 |
| Debt-equity | Debt / Equity | lower = safer |
| Interest coverage | EBIT / Interest | higher = safer |
| Gross margin | GP / Sales x 100 | pricing power |
| Net margin | PAT / Sales x 100 | overall profitability |
| ROA | PAT / Total assets | asset efficiency |
| ROE | PAT / Equity | return to owners |
| Inventory turnover | COGS / Average inventory | speed of selling |
| Operating profit ratio | (Sales - COGS - Opex) / Sales | core efficiency |
Practice problems (with answers)
- ROA: net income 80,000; total assets 5,00,000 → 0.16 (16%).
- Operating profit ratio: sales 15,00,000; COGS 9,00,000; opex 3,00,000 → 3,00,000/15,00,000 = 20%.
- COGS from turnover: inventory turnover 5; opening 1,00,000; closing 1,20,000 → average 1,10,000 x 5 = Rs 5,50,000.
- Quick ratio: CA 4,00,000 (inventory 1,50,000); CL 2,00,000 → 1.25.
- Horizontal analysis: sales 100 (base year) → 120 next year → +20% (index 120).
- Vertical analysis: COGS 60,000 on sales 1,00,000 → 60% of sales.
- Cash flow: profit 50,000; depreciation 10,000; debtors up 8,000; creditors up 5,000 → operating cash flow = 50 + 10 - 8 + 5 = Rs 57,000.
- Short answer (5 marks): Difference between current and quick ratio. → Quick ratio excludes inventory (and prepaid), giving a stricter test of immediate liquidity.